 Analysis by Appwee
When I think about using a credit-building app, the first question isn’t whether it has a polished dashboard; it’s whether its routine fits my budget well enough to keep going. Self – Credit Builder & Cash is a finance app from Self Financial, Inc. built around that practical starting point: making regular payments toward a credit-builder account rather than relying on an existing credit history to qualify. I see it as a structured option for someone who wants to begin building a record of payments and can set aside money consistently.
First Impressions: What’s the Deal with Self?
When you first fire up Self – Credit Builder & Cash, you’re greeted with a clean, user-friendly interface that doesn’t overwhelm you with jargon. It’s like sitting down with a friend who’s ready to walk you through the credit maze. The app’s main goal is simple: help you build credit while saving money. Sounds like a win-win, right?
The sign-up process is straightforward. You answer a few questions, choose a plan, and boom, you’re on your way. What’s cool is that you don’t need an excellent credit score to get started. In fact, it’s designed for folks who are just starting out or need a little boost.
How Does It Work?
Here’s where it gets interesting. Self operates on a credit-builder account model. You pick a plan that suits your budget, and the app sets aside money each month in a certificate of deposit (CD). As you make monthly payments, Self reports these to the credit bureaus. So, essentially, you’re saving money while building credit. It’s like hitting two birds with one stone!
Once you’ve completed the plan, you get the money back (minus interest and fees), which is a nice little bonus. You can choose plans with varying payment amounts and terms – it’s flexible, which I really appreciate.
The key choice is not simply which plan looks affordable on the sign-up screen. I’d compare its recurring payment with the money I can reliably leave untouched each month, after essentials and other bills are covered. The balance is not the same as a cash stash I can freely dip into: it is tied to the account structure until the plan ends, and the amount returned is reduced by interest and fees. That makes Self a poor fit for money I may need for rent, groceries, or an unexpected repair.
Before committing, I’d also read the plan’s payment schedule and account terms carefully. A credit-building routine works best when the due date is easy to remember and the payment is sustainable in an ordinary, slightly inconvenient month—not just in a good one. If there is any doubt, choosing a smaller commitment is more sensible than stretching the household budget for the sake of a credit goal.
More From Our Writers

OTR Makes Off-Road Roaming a Perfect Fit for Short Play Sessions

Prime Video vs. Netflix and Disney+: More Choice, More Clutter

SHAREit Review: A Fast, No-Cloud Way to Move Files

Cryptoguru Makes Crypto Trading Safer, but Can It Teach Restraint?

FC Mobile 26 Turns Soccer into a Season-Long Service

Reddit Is Worth Your Time Only If You Choose Your Communities
Features That Stand Out
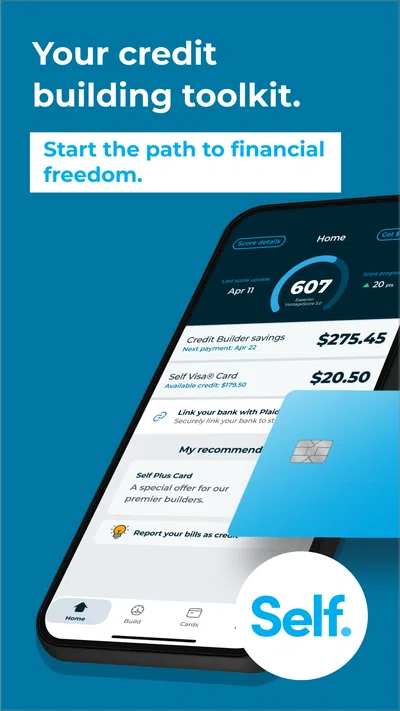
Now, let’s talk features. One of my personal favorites is the payment reminders. Life gets busy, and it’s easy to forget about bills. Self sends timely notifications, so you’re always on track. Plus, the app offers a credit monitoring feature, giving you a snapshot of your credit progress. It’s like having a personal credit coach in your pocket!
Another cool feature is the Self Visa® Credit Card. Once you’ve made three on-time payments and have at least $100 in your credit-builder account, you’re eligible for this secured card. It’s a great way to further build credit with responsible use.
I’d treat the reminders as a backup, not as the whole payment system. Notifications are useful, but they can be missed if a phone is on silent, an alert setting changes, or the notification arrives at a busy moment. My practical approach would be to put the due date in my normal calendar as well, then check the payment status in the app after the scheduled action. That small second check matters because the benefit comes from payments being made on time, not merely from opening the dashboard.
The monitoring screen is most useful as a progress check, rather than a promise that every score movement will be immediate or dramatic. Credit histories change for multiple reasons, and a new positive payment record takes time to become part of a broader picture. I would look for consistency over time and avoid reacting to every small fluctuation by changing plans or taking on additional credit.
Making the Routine Work in Real Life
Picture someone who has started a new job and wants to establish credit, but whose income arrives on a predictable schedule. They could review their monthly bills, choose a payment level that leaves room for essentials, and align reminders with the part of the month when funds are available. After each payment, they can use the app’s progress view to keep the goal visible. This is a modest workflow, but its strength is that it turns an abstract aim—building a credit history—into a repeated action.
There is a useful trade-off here: the account combines saving with credit-building, but the two goals don’t have equal flexibility. The payment discipline can help a person avoid spending the set-aside balance, while that same structure makes the money less convenient than savings held in an ordinary account. I’d keep emergency savings separate and use Self only for money I can commit to the plan.
For someone comparing options, the usual alternatives solve different problems. A regular secured credit card may offer more day-to-day spending flexibility, but it requires careful use and timely repayment; a credit-builder account instead centers on scheduled payments and accumulated savings. A free budgeting or credit-monitoring tool may help someone understand finances without creating the same commitment, but it does not replace a payment history-building product. I’d choose based on the behavior I need help with, not on which option sounds like the fastest route to a higher score.
Who’s It For?
Self is perfect for anyone looking to build or rebuild their credit. Whether you’re fresh out of college, recovering from financial setbacks, or simply want to improve your credit score, this app has something to offer. It’s particularly handy if you’ve been turned down for traditional credit cards due to a lack of credit history.
It’s also a smart choice if you’re looking for a low-risk way to save money. The CD acts as a safety net, so you’re not just throwing money into the void. You’re saving and building credit simultaneously.
I’d be more cautious if you already have a solid credit history and mainly want a card for everyday purchases, rewards, or a short-term borrowing need. Self’s core routine is not a substitute for comparing ordinary card terms or for choosing a product around spending perks. It may also be the wrong tool if your monthly income varies widely, you are juggling overdue essentials, or locking away part of your budget would make an emergency harder to handle. In those situations, stabilizing cash flow comes first.
One question people often have is whether they need good credit to start. The app is aimed at people who are new to credit or trying to improve it, and the credit-builder approach does not depend on already having an excellent score. That still doesn’t mean every applicant or plan will be identical, so I’d review the current eligibility and terms in the app before treating a particular option as guaranteed.
Another sensible question is what happens after the plan finishes. The money is returned after completion, less interest and fees, so I would think of it as committed savings with a defined endpoint rather than a quick-access account. If the main need is cash available at any time, a conventional savings account is a better match. If the aim is to build a payment record while accumulating funds, the trade-off may be worthwhile.
Where the Flow Can Break
The routine depends on consistency, and that is also its main point of friction. A reminder cannot make an unaffordable payment affordable, and a missed or late payment can undermine the very habit the account is meant to encourage. I would not sign up during a month when expenses are already uncertain or assume that the app alone will repair a credit profile. It is one part of a broader financial routine, not a shortcut around budgeting or time.
I’d also keep expectations measured. Credit monitoring can help me notice progress, but it is not a guarantee of approval for a future loan or card, and a score is only one part of a lender’s decision. The most useful outcome may be the steady payment habit and accumulated savings, even if the visible credit change takes patience. If I needed to compare credit options for an imminent application, I’d look at the full picture rather than relying on one app’s progress display.
Self is free to download, is rated for Everyone, and has a 4.4 average from around 91,000 ratings. It has passed over a million installs, which suggests it has found an audience among people looking for a guided credit-building routine. The app was released on March 30, 2018, and version 7.3.0 supports Android 5.0 and later. Those details make it accessible to many Android users, but the important decision is still whether its account terms and recurring commitment fit your own finances.
Final Thoughts: Is It Worth It?
All in all, Self – Credit Builder & Cash is a fantastic tool for anyone serious about improving their credit score. It’s user-friendly, effective, and offers a unique approach to credit building. Sure, there are fees involved, but the benefits of improved credit can far outweigh the costs.
If you’re on the fence, give it a whirl. With its flexible plans and helpful features, Self makes the daunting task of building credit feel manageable, even enjoyable. And who knows, you might just find yourself climbing that mountain with ease!
My recommendation is to start by checking whether the monthly payment fits comfortably, then compare the total cost and timing with the value you place on building credit and saving in one routine. Self makes the most sense when you want structure, can leave the money committed, and are prepared to keep up with payments. If flexibility or immediate access to cash matters more, I’d choose a simpler savings approach or compare other credit products first. The app can make a deliberate plan easier to follow, but the best result still comes from choosing a commitment you can maintain.
Self - Credit Builder & Cards Pros and Cons
- Easy to set up and navigate.
- No credit check required to start.
- Automated savings feature.
- Real-time credit score updates.
- Supports financial goal setting.
- Monthly fees may apply.
- Limited customer support options.
- Can impact credit if not managed well.
- App has occasional glitches.
- Limited features for advanced users.
Self - Credit Builder & Cards Frequently Asked Questions
What is the main purpose of the Self – Credit Builder & Cash app?
The Self – Credit Builder & Cash app is designed to help users improve their credit scores by allowing them to build credit history through small, manageable loans. Users make monthly payments that are reported to major credit bureaus, helping to establish or improve their credit score over time.
How does the credit builder loan work in the Self app?
The credit builder loan in the Self app works by setting up a small loan held in a secured account. Users make monthly payments, which are reported to credit bureaus. Once the loan is paid off, the user receives the amount minus interest and fees, thus building a positive credit history.
Are there any fees associated with using the Self app?
Yes, the Self app includes fees such as a one-time non-refundable administrative fee to set up the credit builder account. Additionally, there are interest fees associated with the loan. Users should review all terms and conditions carefully to understand the total cost involved.
Is the Self app safe to use for managing personal financial information?
The Self app uses industry-standard security measures to protect users' personal and financial information. This includes encryption and secure data storage practices. However, users should always practice caution and ensure they use secure passwords and monitor their accounts regularly.
Can the Self app help me if I already have a good credit score?
While the Self app is primarily designed for those looking to build or improve their credit score, users with good credit can still benefit by maintaining a positive payment history. However, those with excellent credit might find limited additional benefits from using this service compared to other financial products.
Gallery